
What services are taxable? Many services are not taxed in many states, but some services are taxed, and the list differs by state. A service seller who assumes no service is ever taxed will miss tax in states that do tax that service. A seller who taxes every service will overcharge buyers in states where that service is not taxed.
This post answers what services are taxable, for physical services such as repair, cleaning, and consulting, and how states treat them. It is different from the SaaS post, which covers online software by subscription. Read Is SaaS Taxable by State for software. Use this post for services done by a person or a team, with or without goods involved.
What services are taxable: why service rules differ
Sales tax started as a tax on goods. Over time, states added some services to the tax list, one by one, for different reasons. That history is why the list is uneven. One state may tax repair services. Another may tax cleaning services but not repair services. A third may tax almost no services at all, except for a short list.
A service can also be taxed in one state because it is listed by name, and not taxed in another state because it is not listed. The name matters. A service called “repair” in one state law may cover a different set of jobs than a service called “repair” in another state law. Read the state list for the exact service, not just the general category.
Repair services
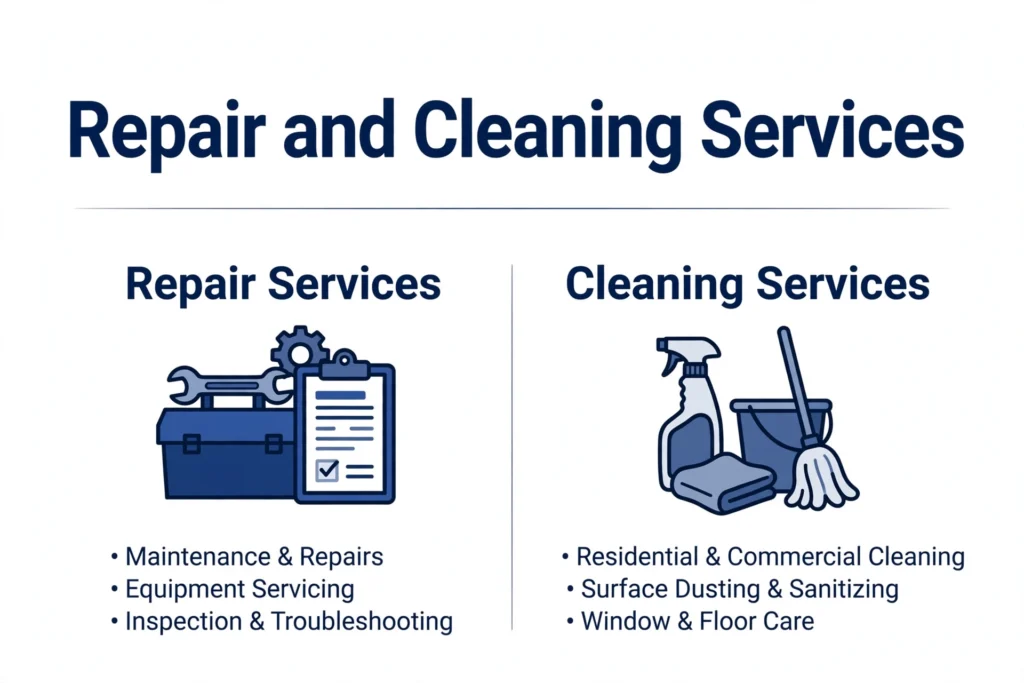
Repair is a common taxable service in many states, but the rule has detail. Repair of tangible goods, such as a phone, a car, or a household item, is often taxable when the repair is done for a buyer in that state. The tax can apply to the labor charge, to parts used, or to both, based on the state rule.
Parts and labor should be stated apart on the invoice, when the state rule treats them differently. For example, a repair job priced at 200 dollars, split into 120 dollars for parts and 80 dollars for labor, at an example rate of 8 percent, would carry different tax based on the state rule.
If both parts and labor are taxed, the tax is 200 dollars times 0.08, which is 16 dollars, and the total is 216 dollars. If only parts are taxed, the tax is 120 dollars times 0.08, which is 9.60 dollars, and the total is 209.60 dollars. If only labor is taxed, the tax is 80 dollars times 0.08, which is 6.40 dollars, and the total is 206.40 dollars. The same job can therefore give three different totals, based on the state rule for parts and labor.
Keep parts and labor apart on every repair invoice, so the tax can be worked out for the state in question, even if the rule changes later.
Cleaning services
Cleaning services are taxed in some states and not in others. The kind of cleaning matters. Cleaning a home, cleaning a business office, cleaning a car, and cleaning clothes can have different rules, even in the same state.
A cleaning service that uses the seller’s own products and tools is usually a service sale. A cleaning service that also sells products to the buyer, such as a cleaning kit, can be a mixed sale of a service and goods. State each part apart on the invoice, so the goods part and the service part can be taxed based on their own rules.
If you clean in more than one state, check the rule for each state where the cleaning happens. A cleaning job is usually taxed where the work is done, not where the seller is based, if the seller and the work location differ.
Consulting and professional services
Consulting, accounting, legal, and similar professional services are not taxed in many states. But some states tax some professional services, or tax a service when it is bundled with a taxable good or a taxable service.
For example, consulting advice given on its own, with no goods and no other taxable service, is often not taxed. Consulting that includes a report, a software setup, or a training session can be treated differently, based on how the state treats the bundle and how the invoice states each part.
If you sell consulting, state each part of the work apart on the invoice: advice time, report writing, training time, and any goods supplied. That split will help you apply the state rule for each part, rather than taxing or not taxing the whole job on a guess.
Services bundled with goods
A bundle is a sale that mixes a service with goods, or mixes two services with different tax treatments. States handle bundles in different ways. Some states tax the whole bundle if one part is taxable. Others allow a split, if the parts are stated apart on the invoice with separate prices. Others tax each part based on its own rule, even if sold together.
Here is a simple bundle example, with an example rate only. A seller sells a taxable good for 100 dollars, plus a non-taxable service for 50 dollars, at a rate of 8 percent. If the state allows a split and the invoice states each part apart, the tax is 100 dollars times 0.08, which is 8 dollars, and the total is 158 dollars. If the state taxes the whole bundle because one part is taxable, the tax is 150 dollars times 0.08, which is 12 dollars, and the total is 162 dollars. The difference is 4 dollars, which is tax on the 50 dollar service part at 8 percent. That difference shows why a clear invoice split matters, and why the state bundle rule must be checked.
How to check a service in your state
Use these steps for each service you sell or buy:
- Write down the exact service, including what is done, where it is done, and what goods, if any, are supplied with it.
- Look for the state revenue department list for that service, by name, not just by general category.
- Check if parts, labor, or goods supplied with the service are taxed apart from the service itself.
- Check if the service is taxed where the work is done, where the buyer is, or where the seller is based, based on the state rule for that service.
- Note the source and the date you checked it, because service lists can change when a state adds a new service to the tax list.
If you cannot find the service on a state list, do not assume it is taxed or not taxed. For goods that may be exempt on their own, read What Items Are Exempt From Sales Tax. In many states, a service is not taxed unless a law lists it as taxable. But that is not true in every state, and some states tax a wide set of services. Check the state rule for that service, and keep the answer with your records.
Checklist for service sellers
- State each service part and each good part apart on the invoice, with separate prices.
- Check the service list for each state where you work, not just your home state. For how to report tax on a service sale, read How to File Sales Tax for Small Business.
- Check parts and labor rules apart for repair jobs.
- Check bundle rules before you sell a service with goods, or two services together.
- Keep the state source and date for each service you rely on.
- Review service lists when you add a new service line.
Taxable Services by State
| State | Repair labor | Cleaning | Professional and consulting |
|---|---|---|---|
| Hawaii | Taxable | Taxable | Taxable |
| New Mexico | Taxable | Taxable | Taxable |
| South Dakota | Taxable | Taxable | Taxable (accountants are named in the statute) |
| West Virginia | Taxable, except repairs that are capital improvements to real property | Taxable | Check the state source |
| Texas | Split: repair of tangible personal property taxable; nonresidential real property repair taxable in full; residential repair labor not taxable | Taxable (janitorial and custodial services) | Not taxable |
| New York | Taxable | Split: interior cleaning and maintenance of buildings taxable; laundering, dry cleaning, carpet, rug, drapery, and upholstery cleaning not taxable | Not taxable |
| California | Not taxable when the charge is itemized; tax applies only to parts and materials | Not taxable | Not taxable |
| Florida | Split: repair of tangible personal property taxable in full, labor included, when parts or materials are supplied; labor-only repair not taxable | Split: nonresidential cleaning taxable; residential cleaning not taxable | Not taxable |
| Ohio | Taxable on the full charge, labor included | Taxable, once the provider reaches $5,000 in gross sales of that service in a calendar year | Not taxable |
| Pennsylvania | Taxable | Taxable (building maintenance or cleaning services; washing, cleaning, waxing, polishing, or lubricating motor vehicles) | Not taxable |
Taxable means the state charges its sales tax (or, for Hawaii and New Mexico, its gross receipts tax) on that service. Sources checked November 6, 2026.
Hawaii charges a General Excise Tax (GET), not a sales tax. It applies to gross income from almost all business activity, including services. Rate 4.5% (4% state plus 0.5% county surcharge).
New Mexico charges a Gross Receipts Tax (GRT), not a sales tax. Receipts from performing a service are subject to GRT unless a specific exemption applies.
Services are taxable by default; a service is exempt only if the law says so.
Frequently asked questions
Are all services taxable?
No. Many services are not taxed in many states. Some services are taxed in some states. The list differs by state, so check the service by name in the state where the work is done.
Is repair labor taxable?
It depends on the state. In some states, repair labor is taxed. In others, only parts are taxed, or only labor is taxed. State parts and labor apart on the invoice.
Is cleaning taxable?
It depends on the state and on the kind of cleaning. Home cleaning, office cleaning, car cleaning, and laundry can have different rules, even in the same state. Check the state list for the exact cleaning service.
Is consulting taxable?
Consulting advice on its own is often not taxed, but the answer can change if consulting is bundled with goods, software setup, or training. State each part apart on the invoice and check the state bundle rule.
What if a service is bundled with goods?
Some states tax the whole bundle if one part is taxable. Others allow a split if the parts are stated apart with separate prices. Check the state bundle rule before you set the total.
This post gives general information only. It is not tax advice. Tax rules change, and they differ by state. Check the service list for your state before you charge tax on a service.